← All insights

City Snapshot – SINGAPORE Q1 2025

City Watch office sector snapshot: Singapore, Q1 2025
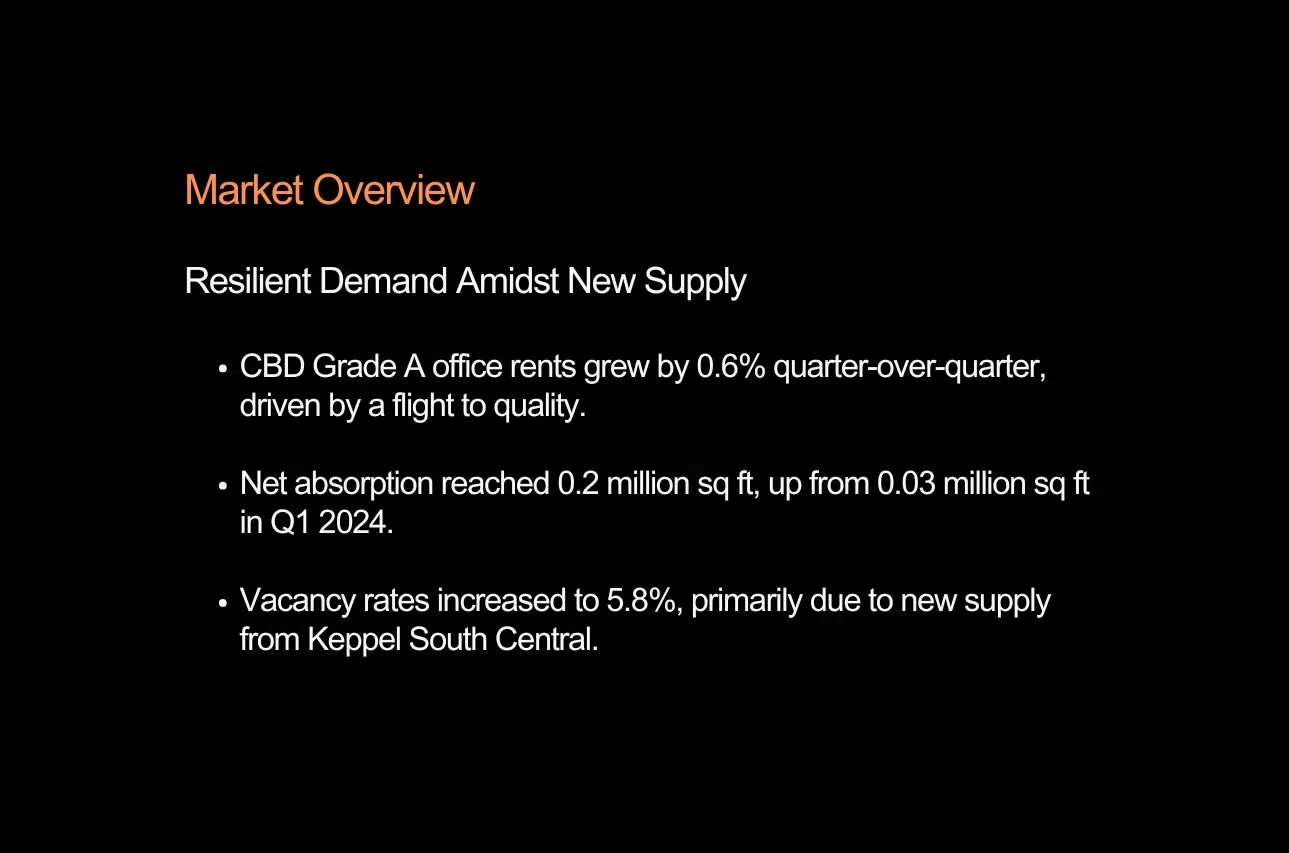
Singapore market overview: resilient demand amid new supply. CBD Grade A rents grew 0.6% quarter on quarter on a flight to quality, net absorption reached 0.2 million sq ft, up from 0.03 million in Q1 2024, and vacancy rose to 5.8%, mainly due to new supply from Keppel South Central.
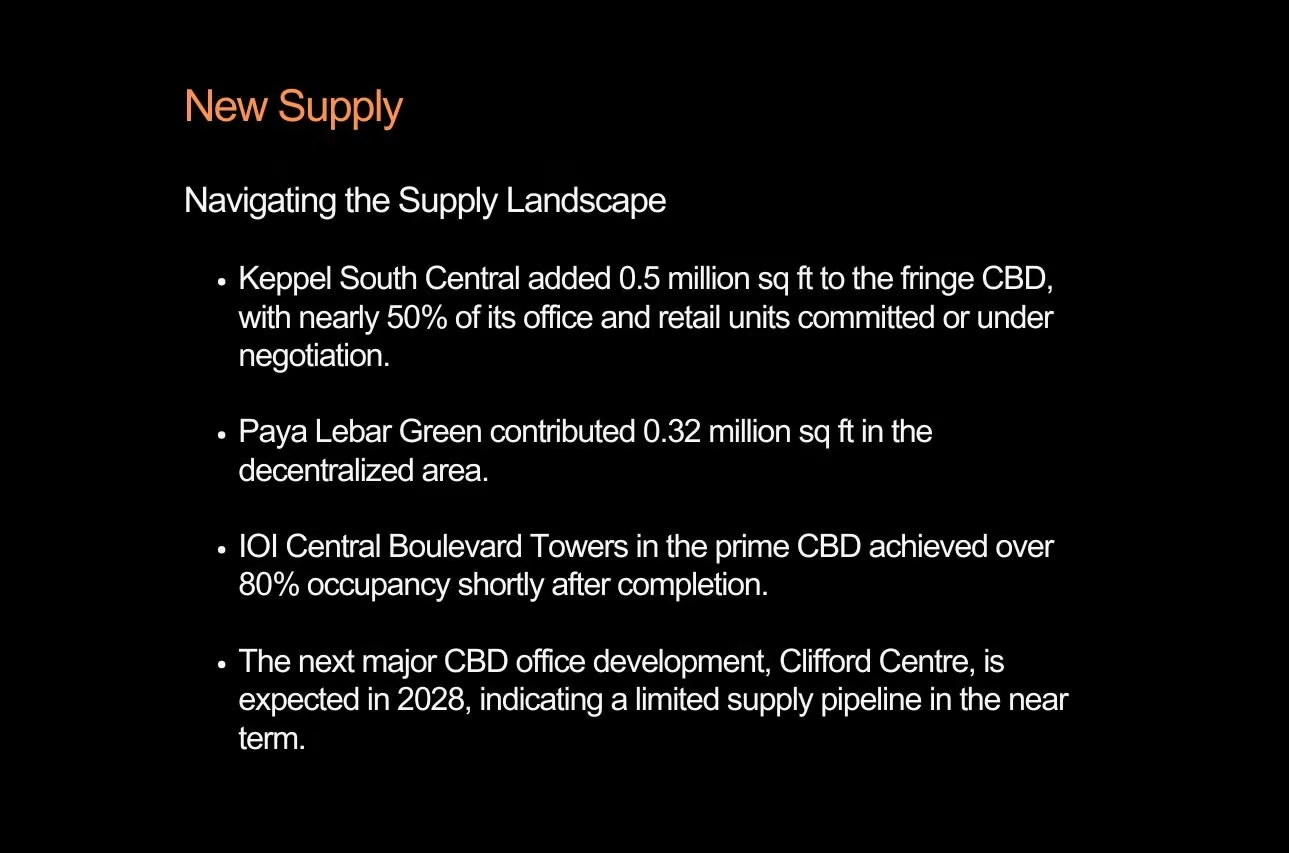
Singapore new supply: Keppel South Central added 0.5 million sq ft to the fringe CBD, Paya Lebar Green added 0.32 million sq ft, IOI Central Boulevard Towers passed 80% occupancy shortly after completion, and the next major CBD development, Clifford Centre, is expected in 2028.
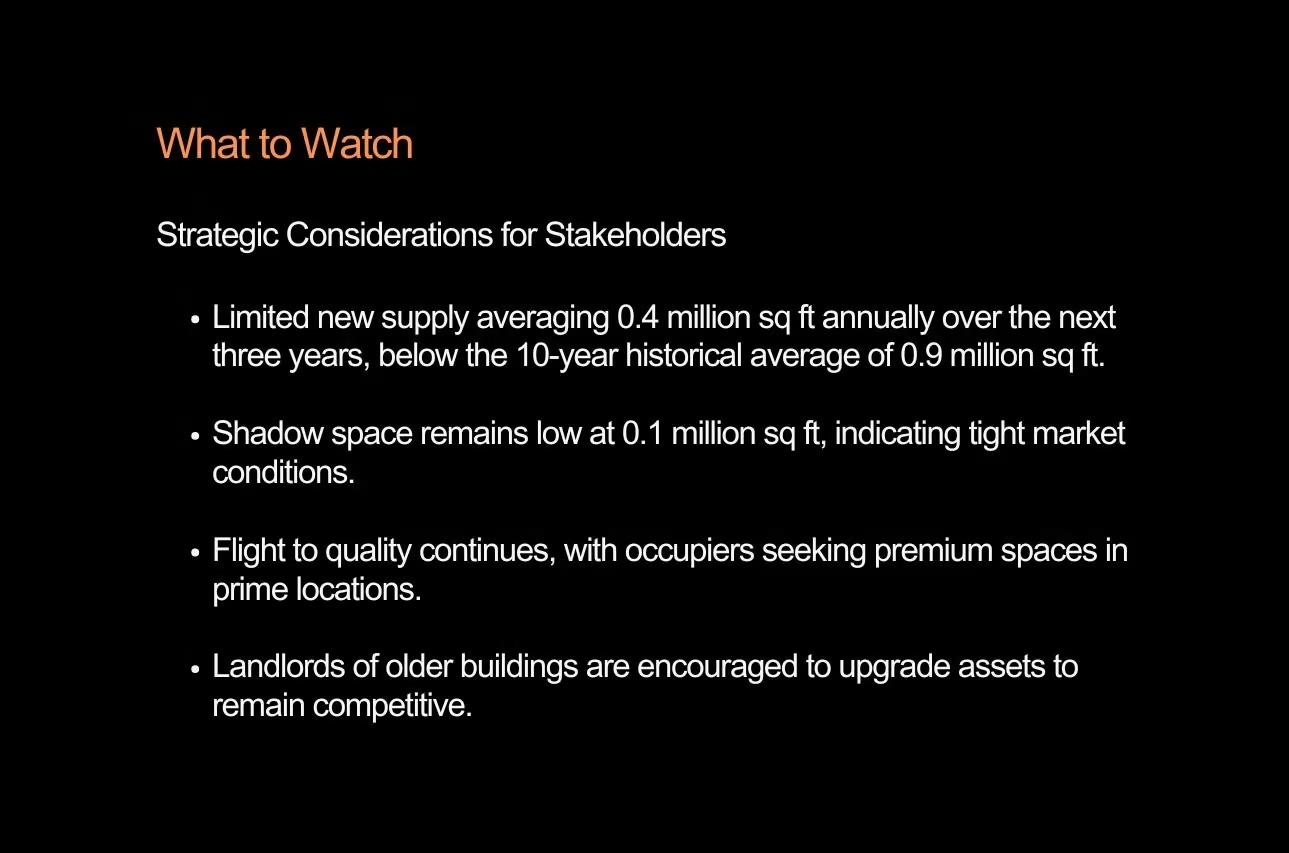
Singapore, what to watch: limited new supply of about 0.4 million sq ft a year over the next three years, below the 10-year average of 0.9 million; shadow space is low at 0.1 million sq ft; the flight to quality continues; and landlords of older buildings are encouraged to upgrade.
Singapore, looking ahead: occupiers should act decisively to secure quality space as supply tightens, and investors may find value in upgrading older assets.
Sources: CBRE, Growth Resumes in Singapore Office Rents in Q1 2025; Cushman and Wakefield, Singapore Office MarketBeat Q1 2025; Colliers, Singapore Office Market Report Q1 2025.
Closing slide: recruitment redesigned, www.re-search.co